Merchandise inventory is the finished product your business buys to resell, and it is recorded at cost as a current asset on your balance sheet. The speed at which your merchandise fulfillment process turns that inventory into cash says a lot about your business's financial health.
To increase revenue through your eCommerce fulfillment, you need to keep a regular check on your inventory and plan your purchasing around it. Besides providing end to end ecommerce fulfillment solutions, ShipBots offers expert assistance with inventory management too.
Read on to find out what merchandise inventory is, how to value and organize it, and how working with ShipBots can make it easier to monitor and manage.
Merchandise inventory is the value of the finished goods your business owns and expects to sell soon. Inventory is at the center of any 3PL fulfillment relationship, and its total value is accounted for at the end of each fiscal year.
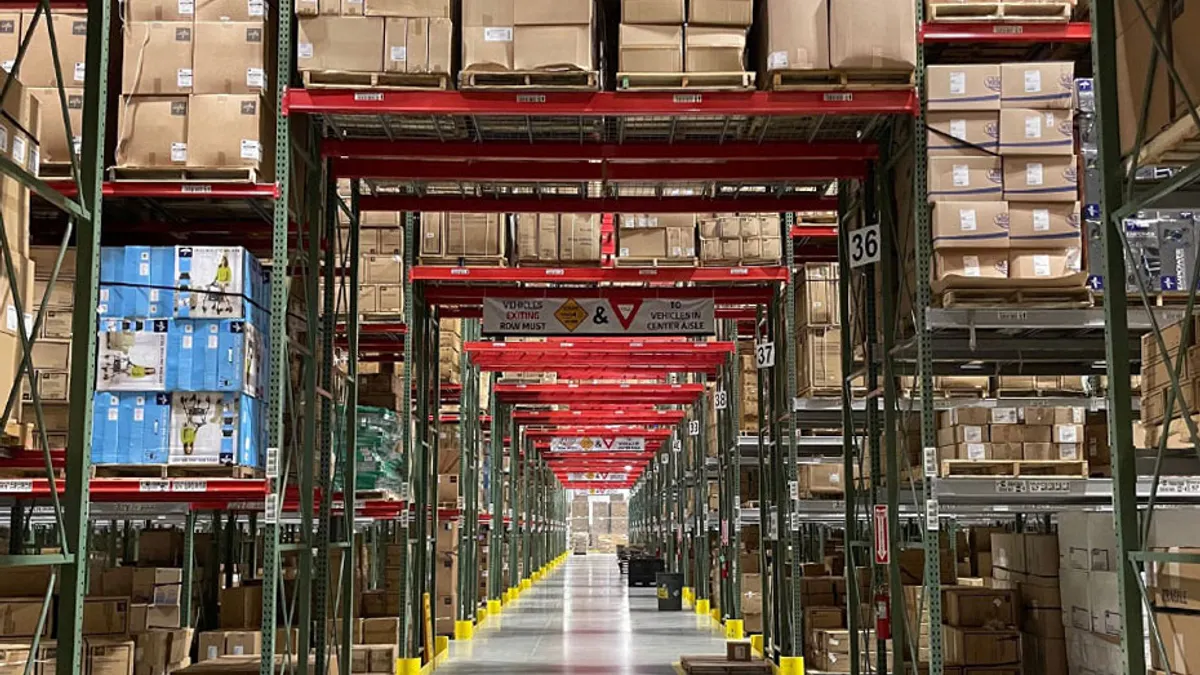
It includes all of the goods your company owns and plans to sell, whether they are in warehouse storage, in transit from your supplier, or stored at a marketplace warehouse such as Amazon FBA. Goods in transit are counted once ownership passes to you, which on freight shipped FOB shipping point happens as soon as the shipment leaves your supplier.
Merchandise inventory should not be confused with manufacturing inventory. Manufacturers track raw materials, work in process inventory, and finished goods as separate categories, while an eCommerce brand that buys finished products only holds the last of these. Packaging supplies such as mailers, poly bags, and tape are also kept separate, since they are used to ship your products rather than sold.
Monitoring and managing merchandise inventory is crucial for a business, because inventory is often the largest asset an eCommerce company has. Your cost of goods sold (COGS) is calculated from your inventory figures, so an inaccurate count will also give you an inaccurate gross margin.
By having a thorough understanding of the important metrics in inventory reporting, businesses can better manage their merchandise inventory. By carefully forecasting customer demand and prioritizing inventory management, businesses can lessen the possibility of stockouts, or of excess inventory that leads to higher carrying costs and more warehouse space.
Inventory valuation can be carried out in different ways depending on which one suits the requirements of your business. However, for the right inventory management, consistency in this choice is essential for precise tracking and valuation.
The valuation method you choose determines which purchase cost is assigned to a unit when it sells, which matters when you have bought the same product at different prices over time. It is an accounting decision, and your warehouse can still ship the oldest units first regardless of which method you use for your books. The most common methods are as follows:
LIFO is permitted under U.S. GAAP, but it is not allowed under IAS 2, the international accounting standard for inventories, and U.S. businesses that want to use it must elect it with the IRS. The IRS explains the rules for inventory methods in Publication 538, so it is worth speaking with your accountant before choosing LIFO.
As an example, suppose your business buys 100 units at $10 each, then another 100 units at $12 each, and sells 120 units during the period. Under FIFO, your COGS would be $1,240 and your ending inventory would be $960. Under LIFO, your COGS would be $1,400 and your ending inventory would be $800. Using the weighted average method, each unit would cost $11, which gives you a COGS of $1,320 and an ending inventory of $880.
Once you've chosen a method that suits your business and supply chain requirements, you will need to stay consistent in using it so that your inventory records remain accurate and comparable from one period to the next.
Essentially, there are two systems for merchandise inventory accounting, namely the Perpetual Inventory System, which keeps a continuous check on inventory levels and value, and the Periodic Inventory System, which updates inventory records at set intervals. Let's take a look at the factors that might make one a better choice over the other for your business.
For most eCommerce businesses, the perpetual system is the better option, particularly once you start selling on more than one channel. A periodic system has no way of keeping your listings accurate between counts, so errors tend to go unnoticed until the next physical count.
To calculate the monetary value of your merchandise inventory, you need to multiply the quantity of unsold inventory in your possession by the cost of each unit. Once found, the value of merchandise inventory is added to the balance sheet as a current asset.
Merchandise inventory value = Cost of each unit x Quantity of unsold inventory
For example, if you have 400 hoodies in stock at a cost per unit of $18, the merchandise inventory value for that SKU is $7,200. Your cost per unit should include inbound freight and import duties as well as the price you paid your supplier.
For calculating the cost of goods sold, or COGS, you need to subtract your ending merchandise inventory value from the sum of the inventory you had at the beginning of the period and the inventory you purchased after.
COGS = (Beginning inventory + Newly purchased inventory value) minus Ending merchandise inventory value
If your business started the quarter with $50,000 in inventory, purchased another $30,000, and ended the quarter with $35,000 on hand, your COGS for the quarter would be $45,000. The same formula can be rearranged to estimate how much inventory you should have before a count, which our ending inventory formula guide explains in more detail. If a physical count comes in lower than expected, the difference is usually due to damage, theft, or receiving errors, and any units that can no longer be sold should be removed through the proper process to write off inventory.
Along with choosing the right valuation method and inventory system, there are a few everyday practices that help keep your merchandise inventory organized and your orders accurate.
Each product variant, including every combination of style, color, and size, should have its own SKU. Using a consistent and readable format, such as HOOD_BLK_M, makes it easier for your team to identify products and reduces picking errors. Our guide to SKU numbers covers formats that work well as your catalog grows.
It also helps to review your catalog regularly with ABC analysis, which groups your products by the revenue they bring in. Your A items, which are usually a small share of your SKUs, tend to generate most of your sales, while C items are slower movers that are more likely to turn into dead stock. A regular SKU analysis will show you which products to reorder, bundle, or discontinue.
Your fastest selling products should be stored in the most accessible locations, close to the packing stations, while slower moving products can be placed higher up or further back in the warehouse. This reduces picking time and the chance of mistakes.
You should also set a reorder point for each SKU, which is calculated by multiplying average daily sales by your supplier's lead time in days and then adding safety stock. For a product that sells 15 units a day, with a 20 day lead time and 100 units of safety stock, you would place a new order once stock drops to 400 units.
Rather than relying on one full count at the end of the year, many businesses count a small portion of their inventory every day or week. A common approach is to count A items monthly, B items quarterly, and C items twice a year. Good stock control of this kind helps you find discrepancies early, when they are easier to trace.
If your business sells on several channels, each of them should draw from the same live inventory count. Without this, you can end up overselling a product on one channel while the same stock goes unsold on another. Our multichannel inventory management checklist explains how to set this up.
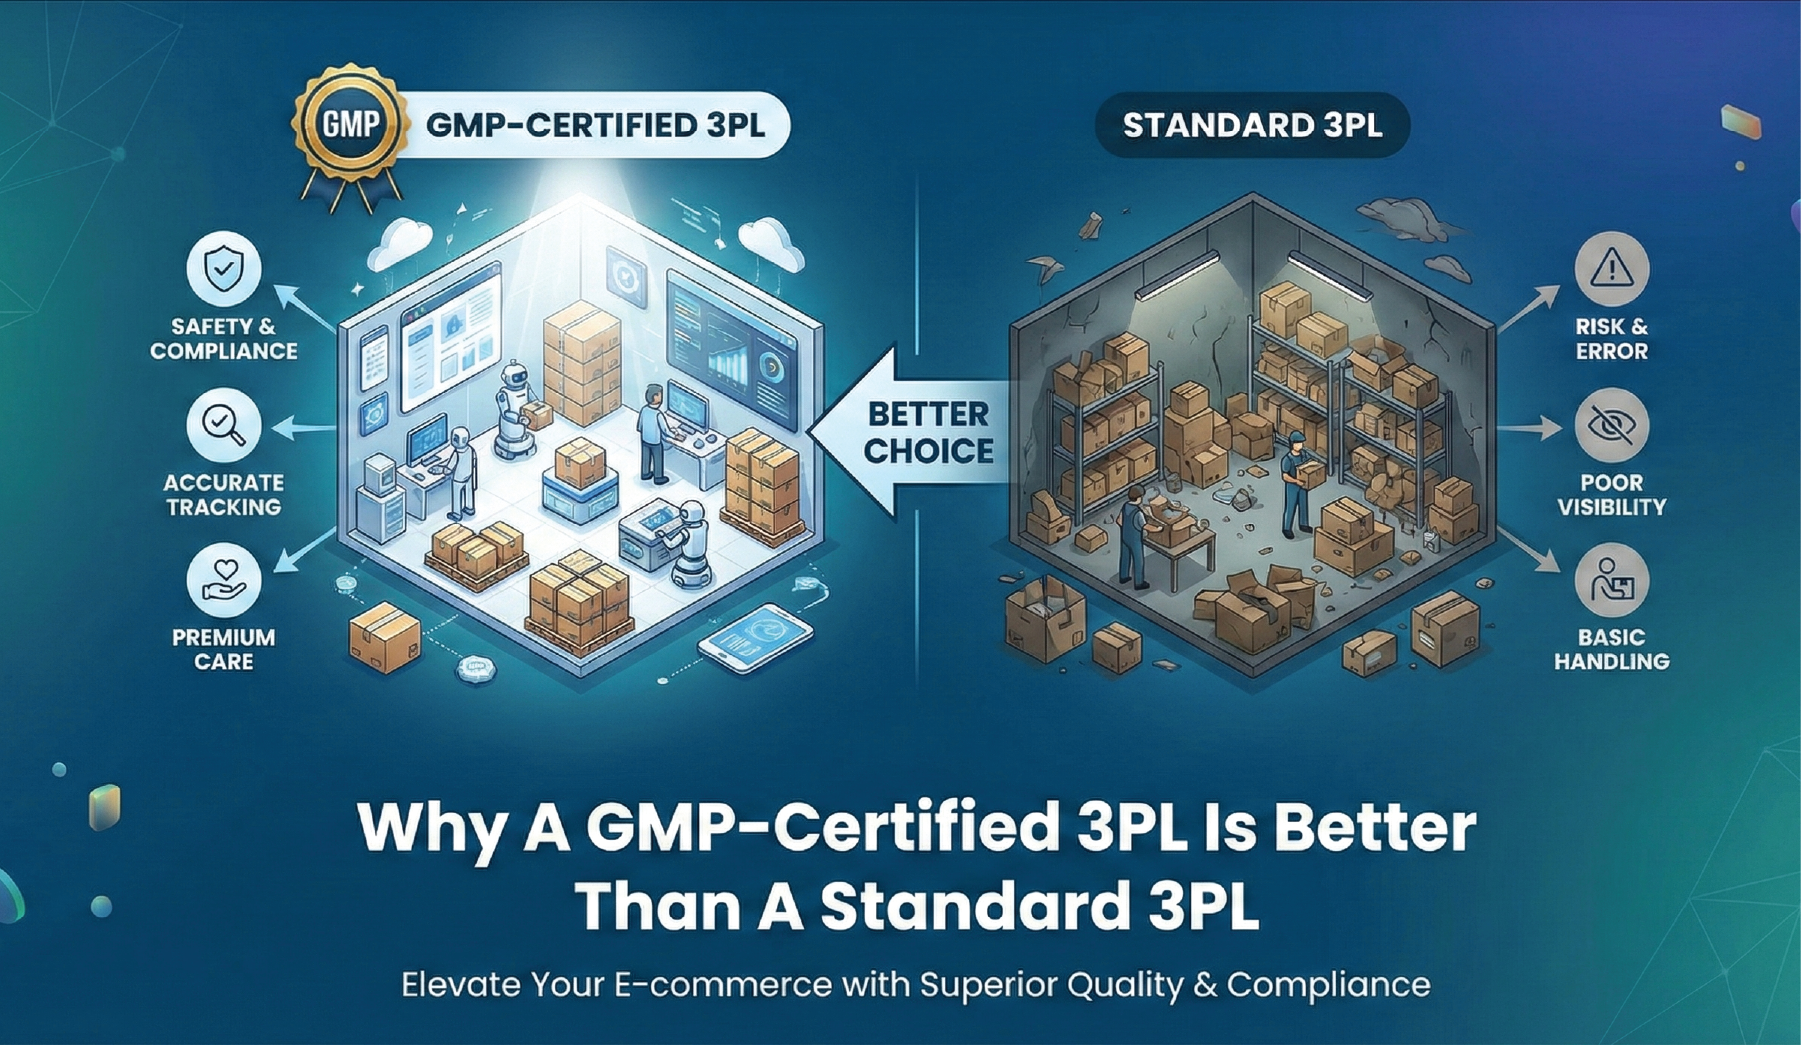
ShipBots specializes in assisting businesses with eCommerce and merchandise fulfillment, from maximizing their dock to stock efficiency and keeping track of inventory with real time software, to splitting inventory across fulfillment centers when needed. Inbound inventory is received within 48 hours, and every order is checked with Vision AI pack verification, which helps ShipBots maintain a 99.999% accuracy rate.
ShipBots can help your growing business cut down on inventory carrying costs through accurate demand forecasting, strategic inventory and warehouse placement, and splitting inventory across fulfillment centers on both U.S. coasts. The Los Angeles fulfillment center is located minutes from the Port of Long Beach, so imported inventory reaches the shelves quickly.
ShipBots enables you to keep tabs on your inventory stock levels in real time, so you can avoid large inventory carrying costs or stockouts. The client portal is powered by ShipHero WMS and shows live inventory by SKU, inbound shipments, and orders from connected channels such as Shopify, Amazon, TikTok Shop, and Walmart.
ShipBots' software lets you stay on top of your business analytics by knowing the precise history of your stock levels, checking which channels are getting the most sales, and seeing which items are not generating enough revenue. ShipBots can also help your business choose the right pick and pack method and strategically choose a warehouse fulfillment location that suits your business needs.
Each client also has a dedicated account manager based inside the warehouse, who can be reached by phone, email, Slack, or SMS, and ShipBots does not require long term contracts.
To learn more about ShipBots and to collaborate with us, you can request a quote and we'll get back to you as soon as possible.
Merchandise inventory is the finished product a business buys to resell without changing it. It includes stock in storage, goods in transit that the business already owns, and units held at a fulfillment center, and it is recorded at cost as a current asset.
Merchandise inventory is an asset. It is classified as a current asset because the business expects to sell it within a year, while any amount still owed to the supplier for that stock is recorded separately as accounts payable.
Under a perpetual system, merchandise inventory is debited when stock is purchased, and its cost is moved to COGS each time a unit sells. Under a periodic system, purchases are recorded in a purchases account, and the inventory balance is adjusted after a physical count at the end of the period.
Purchases are the total cost of the stock a business bought during a period, while merchandise inventory is the value of the stock it has on hand at a specific point in time. Purchases add to merchandise inventory, and sales move that cost out of inventory and into COGS.
Merchandise inventory includes goods in transit if the business already owns them. Under FOB shipping point terms, ownership transfers when the goods leave the supplier, while under FOB destination terms, the goods only become part of your inventory once they arrive